What is the defining scope and industry significance of the Online Legal Services Market?
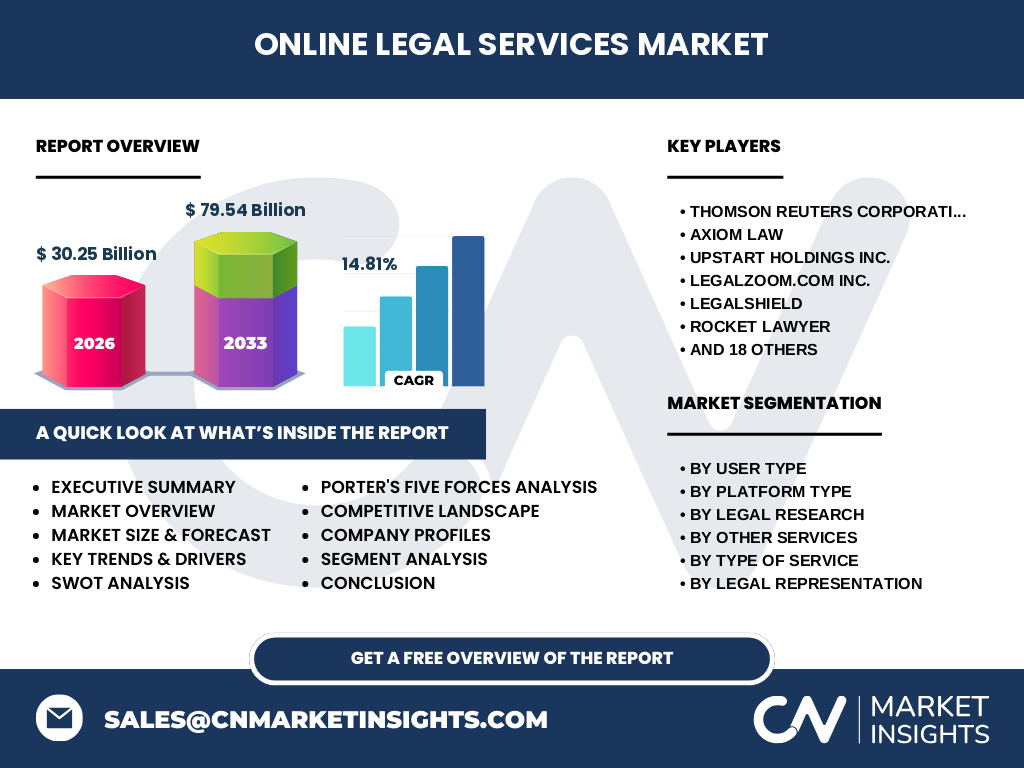
Our analysis indicates that the Online Legal Services Market represents a fundamental restructuring of traditional legal delivery, encompassing digital platforms that streamline access for individuals and enterprises. Valued at 30.25 Billion in 2026, this sector bridges regulatory complexity and modern technological efficiency, mitigating historical barriers imposed by traditional bar associations and localized law firms.
What are the core market drivers, restraints, challenges, and opportunities shaping the Online Legal Services Market?
Growth is propelled by rising consumer demand for cost-effective alternatives to billable-hour models, tempered by strict unauthorized practice of law (UPL) regulations enforced by bodies like the American Bar Association. Opportunities flourish in automated compliance and cloud-based contract lifecycle management, driven by pioneers such as Ironclad and Rocket Lawyer.
Emerging trends and growth patterns in the Online Legal Services Market
The shift toward generative artificial intelligence and automated drafting tools is redefining how firms handle Case Law Research and Statutory Research. Companies like Thomson Reuters Corporation and LegalZoom.com Inc. are leveraging advanced natural language processing to accelerate document turnaround, reducing reliance on manual paralegal workflows.
COVID-19 impact analysis on the Online Legal Services Market and its recovery trajectory
The pandemic acted as an unprecedented catalyst, forcing courts, arbitration bodies, and legal practitioners to adopt remote workflows overnight. This accelerated digital adoption permanently expanded the addressable market, establishing remote consultations and virtual court representation as permanent operational fixtures rather than temporary emergency measures.
Competitive benchmarking and strategic dynamics within the Online Legal Services Market
Market concentration features a split between high-volume consumer platforms and specialized enterprise contract automation tools. Key players like Axiom Law, LegalShield, and Lexly AB compete through distinct value propositions, ranging from subscription-based personal legal plans to flexible, on-demand corporate counsel networks.
Executive summary of key findings regarding the Online Legal Services Market
The data projects the market to surge from 30.25 Billion in 2026 to 79.54 Billion by 2033, expanding at a robust 14.81% CAGR. This exponential trajectory reflects widespread digital transformation across both retail consumer segments and enterprise legal departments seeking operational cost optimization.
Market forecast trajectory from 2027 to 2033
Our research indicates sustained double-digit expansion, scaling the market from its 2026 baseline toward the 79.54 Billion by 2033 valuation at a 14.81% CAGR. This forecast is underpinned by increasing smartphone penetration and the broader acceptance of electronic signatures under the ESIGN Act and global equivalents.
Segmentation analysis across user types, platform types, and legal practice areas
Segmentation spans user types including Individuals, Small And Medium-sized Enterprises (SMEs), and Large Enterprises. Platforms deploy via Websites and Mobile Applications, delivering core offerings such as Legal Document Preparation, Trademark And Patent Filing, and Mediation And Arbitration Services via firms like MyCase and PracticePanther.
Geographic distribution and regional performance in the Online Legal Services Market
Regional adoption heavily correlates with broadband infrastructure maturity and local regulatory flexibility surrounding alternative legal service providers (ALSPs). North America currently commands the dominant revenue share, driven by high venture capital investments in legal tech startups and widespread consumer trust in web-based transactional portals.
In-depth regional review of regulatory environments and market maturity
While North America leads in platform innovation through innovators like Upstart Holdings Inc. and JustAnswer, the European market navigates complex GDPR constraints regarding client data privacy. Meanwhile, Asia-Pacific represents the fastest-growing frontier, propelled by expanding digital economies in Southeast Asia and regulatory modernization.
Strategic positioning of leading companies in the Online Legal Services Market
Industry leaders maintain distinct competitive moats: LegalMatch and LawDepot capture mass-market consumer demand for self-help forms, while Priori Legal Inc. and UpCounsel curate high-end enterprise networks connecting businesses with vetted, independent corporate attorneys for specialized advisory mandates.
Porter's Five Forces analysis of competitive intensity
Competitive rivalry is intense due to low barriers to entry for basic document generators, though mitigated by proprietary legal databases held by giants like Thomson Reuters Corporation. Threat of substitution remains moderate, as complex litigation still requires human advocacy, while buyer bargaining power is high due to transparent online pricing.
SWOT analysis evaluating industry vulnerabilities and advantages
Strengths include low marginal fulfillment costs and 24/7 accessibility; weaknesses involve public skepticism regarding DIY legal accuracy. Opportunities lie in emerging markets and AI-driven predictive litigation analytics, whereas threats stem from evolving data security mandates and aggressive state bar scrutiny over non-lawyer ownership of legal platforms.
Value chain analysis detailing industry structure from technology input to end-user delivery
The value chain originates with raw legal statutes, judicial case law databases, and regulatory filings. These inputs are synthesized by legal engineers and software developers into structured SaaS platforms, which are then marketed via digital acquisition channels to end-users ranging from pro se litigants to enterprise general counsels.
Strategic investment insights and high-potential monetization avenues
Investors should prioritize B2B compliance automation and niche vertical platforms catering to specialized industries like healthcare and fintech regulations. Firms offering integrated billing, case management, and AI research—such as LegisOne and LawTrades Inc.—demonstrate superior customer lifetime value metrics.
Conclusion and key strategic takeaways for market stakeholders
The Online Legal Services Market is transitioning from a disruptive novelty into the mainstream infrastructure of global jurisprudence. Reaching 79.54 Billion by 2033 demands that legacy firms and digital startups alike embrace secure, automated, and client-centric digital workflows to capture expanding market share.
Research methodology and data triangulation techniques utilized in this report
Our baseline estimates are rigorously triangulated by combining corporate registry filings, primary executive interviews with stakeholders from companies like LegalVision and NetLaw Inc., and secondary macroeconomic indicators tracking global legal spending, software adoption rates, and digital signature transaction volumes.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue streams generated through subscription fees, transactional document sales, and SaaS licensing for online legal platforms through 2033. Excluded from this scope are traditional offline billable-hour revenues generated by brick-and-mortar law firms operating entirely outside digital intake channels.
Recent developments, strategic partnerships, and product launches shaping the industry
Recent market dynamism is highlighted by aggressive platform consolidations and strategic integrations of generative AI tools across established players like Lawpath Operations, DirectLaw Inc., and LegalNature, aimed at automating complex multi-jurisdictional filings and enhancing client intake conversion rates.